What Is Clean Energy and Its Sources for Global Buyers?
Clean energy is reshaping how global buyers secure electricity, manage costs, and reduce operational emissions. The term covers power produced with limited greenhouse gas emissions, including solar, wind, hydropower, geothermal energy, and sustainably sourced bioenergy. It also includes enabling technologies such as batteries, smart grids, and green hydrogen. These systems are not identical. Each has different costs, risks, land needs, and supply-chain requirements.
“The clean energy transition is happening worldwide and it’s unstoppable,” says Fatih Birol, Executive Director of the International Energy Agency. “It’s not a question of ‘if’, it’s only a matter of ‘how soon’—and the sooner the better for all of us.” His observation reflects a market already visible in practical places: solar panels covering factory roofs, wind turbines supplying coastal industrial zones, and battery systems balancing power after sunset.
For international buyers, choosing among clean energy sources requires more than comparing advertised prices. Buyers should examine resource quality, grid access, project maturity, warranties, certification, and lifecycle emissions. A low-cost solar contract may still create challenges if transmission capacity is weak. A renewable energy certificate may support accounting goals, but it does not always mean new generation was built. These details matter.
No energy source is perfect. That is the uncomfortable part. Responsible procurement therefore combines verified data, experienced technical review, and clear supplier questions. This guide explains the major clean energy sources, their commercial uses, and the evidence global buyers should request before signing a long-term agreement.
Clean Energy Defined: Emissions, Sustainability, and IEA Accounting Rules
For global buyers, clean energy is not simply electricity labelled green. It usually means energy with very low greenhouse-gas emissions across its life cycle. The IEA’s Global Energy Review 2024 reports that renewables supplied about 30% of global electricity in 2023. The IEA Renewables 2024 report also recorded nearly 510 gigawatts of new renewable capacity that year. Solar and wind expanded quickly, yet grids, storage, hydropower, and firm generation remain important. A solar panel has no smokestack. Its manufacturing still requires minerals, heat, and transport.
Accounting changes the answer. Location-based Scope 2 reporting uses average grid emissions, while market-based reporting uses qualifying contractual evidence. IEA energy statistics can support national grid factors, but they do not replace supplier and contract checks. The IPCC’s Sixth Assessment Report places wind and solar among the lowest lifecycle-emission technologies, although results vary by site, technology, and methodology. For a factory buyer, the practical questions are specific: What was generated, where, when, and under which emissions factor? An annual certificate may match total electricity use while hourly demand still draws from a fossil-heavy grid. That gap is easy to miss. A clean-energy claim can be technically valid yet environmentally incomplete. I would treat this limitation as part of responsible procurement, not as a footnote.
Solar and Wind: IRENA’s 3,870 GW Renewable-Capacity Baseline in 2023
What Is Clean Energy and Its Sources for Global Buyers?
Solar and Wind: IRENA’s 3,870 GW Renewable-Capacity Baseline in 2023
Clean energy comes from sources that produce little or no direct greenhouse-gas emissions during operation. For global buyers, the main choices include solar, wind, hydropower, geothermal, and sustainable bioenergy. Each source behaves differently across seasons, locations, and grid conditions.
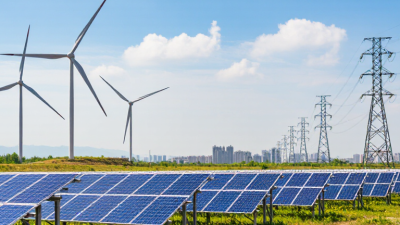
The International Renewable Energy Agency reported 3,870 GW of renewable power capacity worldwide in 2023. Solar and wind provided the largest shares of this baseline. Solar capacity reached roughly 1,420 GW, while wind capacity exceeded 1,000 GW. These figures show strong investment, not guaranteed electricity at every hour.
Capacity is not the same as delivered power. A solar project may generate less on cloudy winter days. Wind output can change within minutes. Buyers should examine resource assessments, grid connection studies, storage plans, and verified production records before signing supply agreements. Site visits can reveal practical details, such as dusty panels, difficult access roads, or limited maintenance crews.
The numbers are impressive. They are also incomplete.
Procurement teams should compare carbon accounting methods, contract terms, local regulations, and delivery risks. Renewable certificates may support claims, but their quality and traceability require careful review. A project with excellent equipment can still underperform because of weak grid infrastructure or unrealistic forecasts. Clean energy purchasing therefore needs technical checks, transparent documentation, and room for uncertainty.
Nuclear, Hydrogen, and Storage: Options for 24/7 Low-Carbon Energy Supply
Global buyers need electricity that stays available after sunset, during winter peaks, and through calm weather. Nuclear power offers firm, low-carbon generation with a small land footprint. The IPCC reports a median lifecycle emission intensity of about 12 grams of CO2-equivalent per kilowatt-hour for nuclear power. However, construction schedules and financing remain difficult. Delays can change the economics.
Hydrogen may serve industry, shipping, and seasonal power storage. The International Energy Agency reports that low-emissions hydrogen still represents less than 1% of global hydrogen production. Electrolysers can absorb surplus renewable electricity, while stored hydrogen can run turbines during prolonged shortages. The drawback is visible: conversion losses are high. Using hydrogen for every daily power cycle is usually less efficient than using batteries directly.
Storage technologies fill different time gaps. Batteries can respond within milliseconds, supporting frequency control and evening demand. The IEA’s Batteries and Secure Energy Transitions report notes that global battery storage deployment rose sharply in 2023, yet longer-duration systems remain less mature. Thermal storage, pumped hydropower, compressed air, and hydrogen may cover hours or seasons. No single solution fits every grid. Buyers should compare hourly demand, grid connection limits, carbon accounting, water availability, and delivery risk. A practical tender may combine nuclear baseload, renewable contracts, batteries, and carefully limited hydrogen backup. It is not perfectly simple. That is the point.
Global Buyer Metrics: Renewables’ 30% Share of Power Generation in 2023
Clean energy comes from sources that produce little or no greenhouse gas during operation. Common sources include solar, wind, hydropower, geothermal energy, and sustainably managed bioenergy. For global buyers, the practical question is not only where power comes from. It is also how reliably that power reaches factories, warehouses, and data facilities.
30%
Renewables supplied 30% of global electricity generation in 2023, according to Ember’s Global Electricity Review 2024. This share marks a major shift in the power market. Hydropower remained the largest renewable source, while solar and wind recorded strong generation growth. The International Renewable Energy Agency reported
473 gigawatts
of renewable capacity additions in 2023. Renewables represented about
86%
of new global power capacity that year.
These figures matter for procurement teams. A buyer can compare renewable availability, hourly output, grid stability, and delivered electricity costs across regions. Solar power may offer low daytime prices, but production falls after sunset. Wind output can change quickly. Storage and stronger transmission networks help reduce these gaps. The International Energy Agency also identifies clean electrification and renewable expansion as central to future energy investment.
The numbers need careful reading. A 30% global share does not mean every market has equal access. Some buyers still face weak grids, unclear certificates, or limited project data. Reported capacity can also hide curtailment and seasonal shortages. Better purchasing decisions require verified generation records, transparent emissions accounting, and local grid evidence. Mistakes remain possible. That is why independent technical checks deserve budget and time.